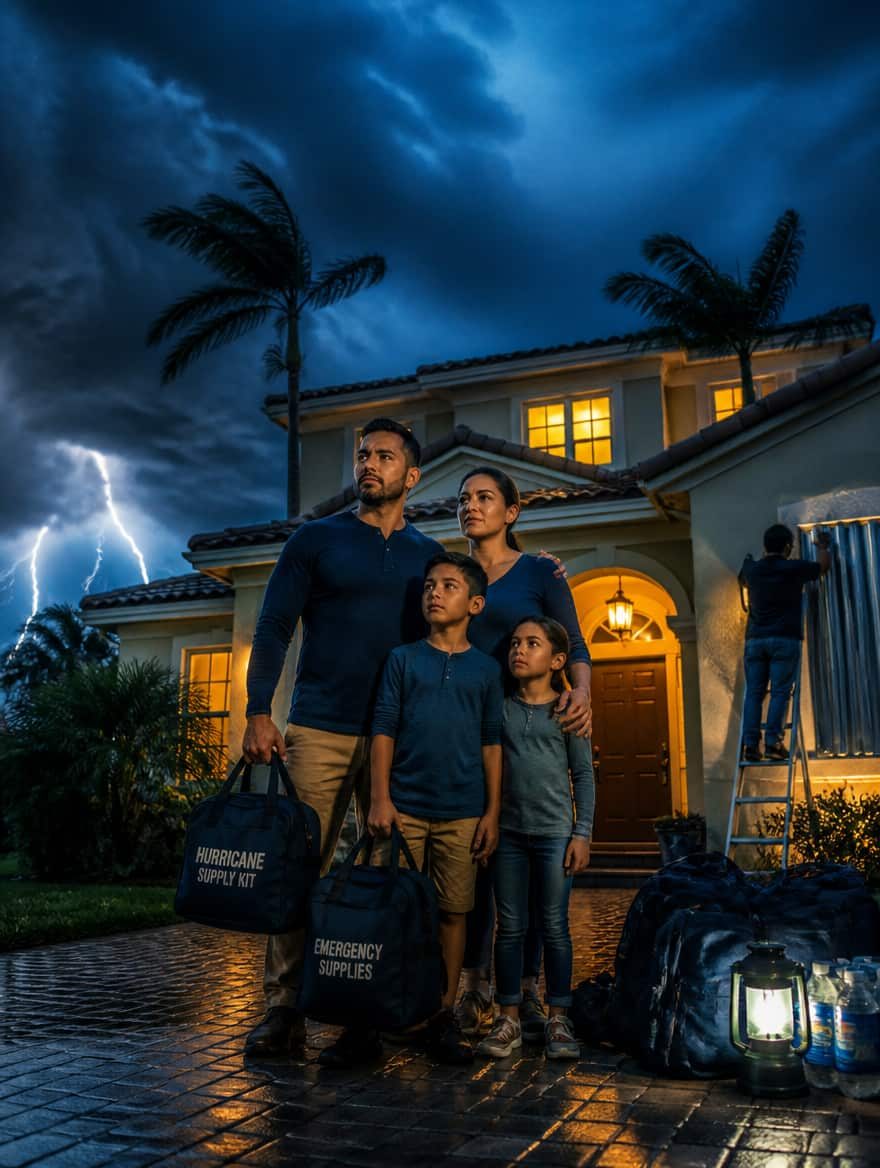
The hurricane season in Florida officially begins on June 1 and ends on November 30. Whether you are a homeowner, a small business owner, or simply living in Florida with your family, May is the perfect month to get ready. Don’t wait until a storm is approaching to act, because by then, it’s already too late.
According to the National Oceanic and Atmospheric Administration (NOAA), the 2025 hurricane season was extremely active, with 18 named storms, and experts predict that 2026 could follow the same trend due to warming Atlantic waters. In Florida, 60% of hurricane damages are not covered by insurance because people either don’t have the right coverage or don’t understand what they have.
Why May Is the Ideal Time to Prepare
May is like that last month of calm before the storm—literally. Prices for materials like plywood, generators, and emergency supplies are still normal. In June and July, when the weather forecast starts to look more serious, these prices skyrocket. Additionally, insurance companies are more open to making changes to your policies now than when a storm is already on the radar.
Review Your Home Insurance NOW (Not in June)
Here’s the problem: many Latino families have basic homeowners insurance, but don’t realize that this insurance often does NOT cover flood damage. Yes, you read that right. Typical homeowners insurance covers wind damage (like when the roof blows off), but if water enters your home due to flooding, that’s a completely different matter.
According to the National Flood Insurance Program (NFIP), only 35% of homeowners in high-risk areas of Florida have flood insurance. But here’s the interesting part: 25% of flood claims come from areas NOT classified as “high risk.” This means that even if you don’t live near water, you could still have problems.
What You Should Do with Your Insurance:
- Call your insurance agent this month. Ask specifically: “Do I have flood coverage?” If the answer is no, ask how much it costs to add it. Flood insurance policies have a 30-day waiting period before they become active, so if you buy one in June, it won’t be active until July.
- Check your policy’s deductible. Many policies in Florida have special hurricane deductibles that can be 2% to 10% of your home’s insured value. If your home is insured for $300,000 and you have a 2% deductible, you pay $6,000 out of pocket before insurance pays anything. Do you have that money saved?
- Document everything you own. Take photos or videos of every room in your house, your furniture, your clothes, your appliances. If something happens, this will be your proof for the insurance company. Store these photos in the cloud (Google Photos, iCloud) or email them to yourself—not just on your phone.
For Small Business Owners: Your Business Needs Protection Too
If you own a business—whether it’s a food truck, an auto repair shop, a beauty salon, or you work in construction with your own tools—you need to think about how to protect your source of income.
The Small Business Administration (SBA) reports that 40% of small businesses never reopen after a natural disaster. Not because the owner doesn’t want to, but because they don’t have the money to rebuild or don’t have insurance.
What to Do if You Own a Business:
- Commercial Property Insurance: Covers your building, equipment, inventory, and furniture. If you rent your space, you still need insurance for your contents.
- Business Interruption Insurance: This is the one many forget. If a hurricane shuts down your business for two months, how will you pay rent, employees, your personal bills? This insurance covers lost income while you can’t operate.
- Create an Emergency Plan: Where will you store your important documents? Do you have digital copies of contracts, licenses, client information? Is your most valuable equipment specifically insured?
Physically Prepare Your Home
It’s not all about insurance. You also need to make your home more resilient:
- Check the roof: Loose or damaged shingles are an invitation for the wind to rip off your entire roof. A roofer can do an inspection for $100-200.
- Clean drains and gutters: If they’re clogged with leaves, water won’t flow properly and can cause flooding in the roof or foundation.
- Trim tree branches near your house: A large branch that falls can pierce your roof or break windows.
- Get shutters or plywood: If you don’t have storm shutters, measure your windows now and buy the plywood you’ll need. Cut and label it for each window. When a storm comes, you can install it in minutes instead of hours.
- Check your generator: If you have one, change the oil and test it. If you don’t have one and your budget allows, consider buying one now. A basic 3,500-watt generator costs around $400-500 and can keep your refrigerator and some lights running.
Prepare Your Family Emergency Kit
According to the Federal Emergency Management Agency (FEMA), every family should have supplies for at least 3 days, but in reality, it’s better to have enough for 7 days. After Hurricane Ian in 2022, many families were without electricity or water for more than a week.
Your Kit Should Include:
- Water: 1 gallon per person per day (family of 4 = 28 gallons for 7 days)
- Non-perishable food: canned goods, rice, beans, pasta, baby food if you have young children
- Manual can opener
- Prescription medications for at least 2 weeks
- First aid kit
- Flashlight and extra batteries
- Battery-powered or hand-crank radio
- Important documents in waterproof bags (passports, birth certificates, immigration papers, property titles, insurance policies)
- Cash (ATMs don’t work without electricity)
- Fully charged portable phone charger
- Hygiene items
- Diapers and formula if you have babies
Special Considerations for Immigrant Families
If you have family members who don’t speak English or who are elderly, make sure they also understand the plan. Many emergency alerts come in English first.
If you have a pending immigration status or are in the process of adjustment, keep copies of ALL your immigration papers in a safe and accessible place. If you have to evacuate quickly, you need to be able to take them with you.
FEMA and other federal disaster assistance programs are available to many immigrants, including permanent residents. Don’t let fear stop you from seeking help if you need it after a storm.
Plan Your Evacuation Route
Do you know what you would do if an evacuation is ordered? Many families say “we’ll stay” without really understanding what a category 3, 4, or 5 hurricane means.
- Identify your evacuation zone: Go to FloridaDisaster.org and enter your address. It will tell you if you are in an evacuation zone and what your official route is.
- Have a place to go: Family in another city? Friends? A hotel? Plan it now, not when everyone is trying to leave at the same time.
- Fill up your gas tank: When a storm is announced, gas stations run out of fuel within hours.
How La Familia Multiservices Can Help You
We understand that all of this can be overwhelming, especially if it’s your first hurricane season or if you’re not sure what insurance coverage you have.
Our team can:
- Review your current homeowners insurance policy and explain exactly what is and is NOT covered
- Help you get flood insurance at the best price
- If you have a business, design a commercial insurance package to protect your investment
- Ensure your important documents (including immigration papers, property titles, business documents) are organized and protected
Don’t wait. In the weeks before a storm, insurance companies stop accepting new applications or changes. May is YOUR time to act.
The Cost of Not Preparing
According to a 2024 University of Florida study, families who did not have adequate insurance after Hurricane Ian spent an average of $45,000 out of pocket on repairs. Many had to take out high-interest loans or use credit cards. Some lost their homes completely because they couldn’t afford the repairs.
Flood insurance costs an average of $700 a year in Florida (less than $60 a month). Is it worth risking losing $45,000 to save $60 a month?
Take Action Today
Don’t put this off. Do these three things this week:
- Call your insurance agent (or call us) and ask specifically about flood coverage and your hurricane deductible.
- Physically inspect your home: roof, trees, windows. Make a list of what needs to be fixed.
- Start your emergency kit. You don’t have to buy everything at once. Every time you go to the supermarket, add a few extra canned goods, a pack of batteries, bottled water.
Preparation isn’t about being afraid—it’s about being smart and protecting everything you’ve worked so hard for. Your family, your home, and your business deserve it.
References:
- NOAA (National Oceanic and Atmospheric Administration) – Hurricane season forecasts
- NFIP (National Flood Insurance Program) – Coverage and claims statistics
- SBA (Small Business Administration) – Post-disaster business recovery statistics
- FEMA (Federal Emergency Management Agency) – Preparedness guides
- University of Florida – Hurricane economic impact studies (2024)
- FloridaDisaster.org – Official state evacuation zones and resources
Do you need help reviewing your insurance or preparing your business for hurricane season? Visit www.lafamiliamultiservices.com or call us. We’re here to help you protect what matters most.