Language
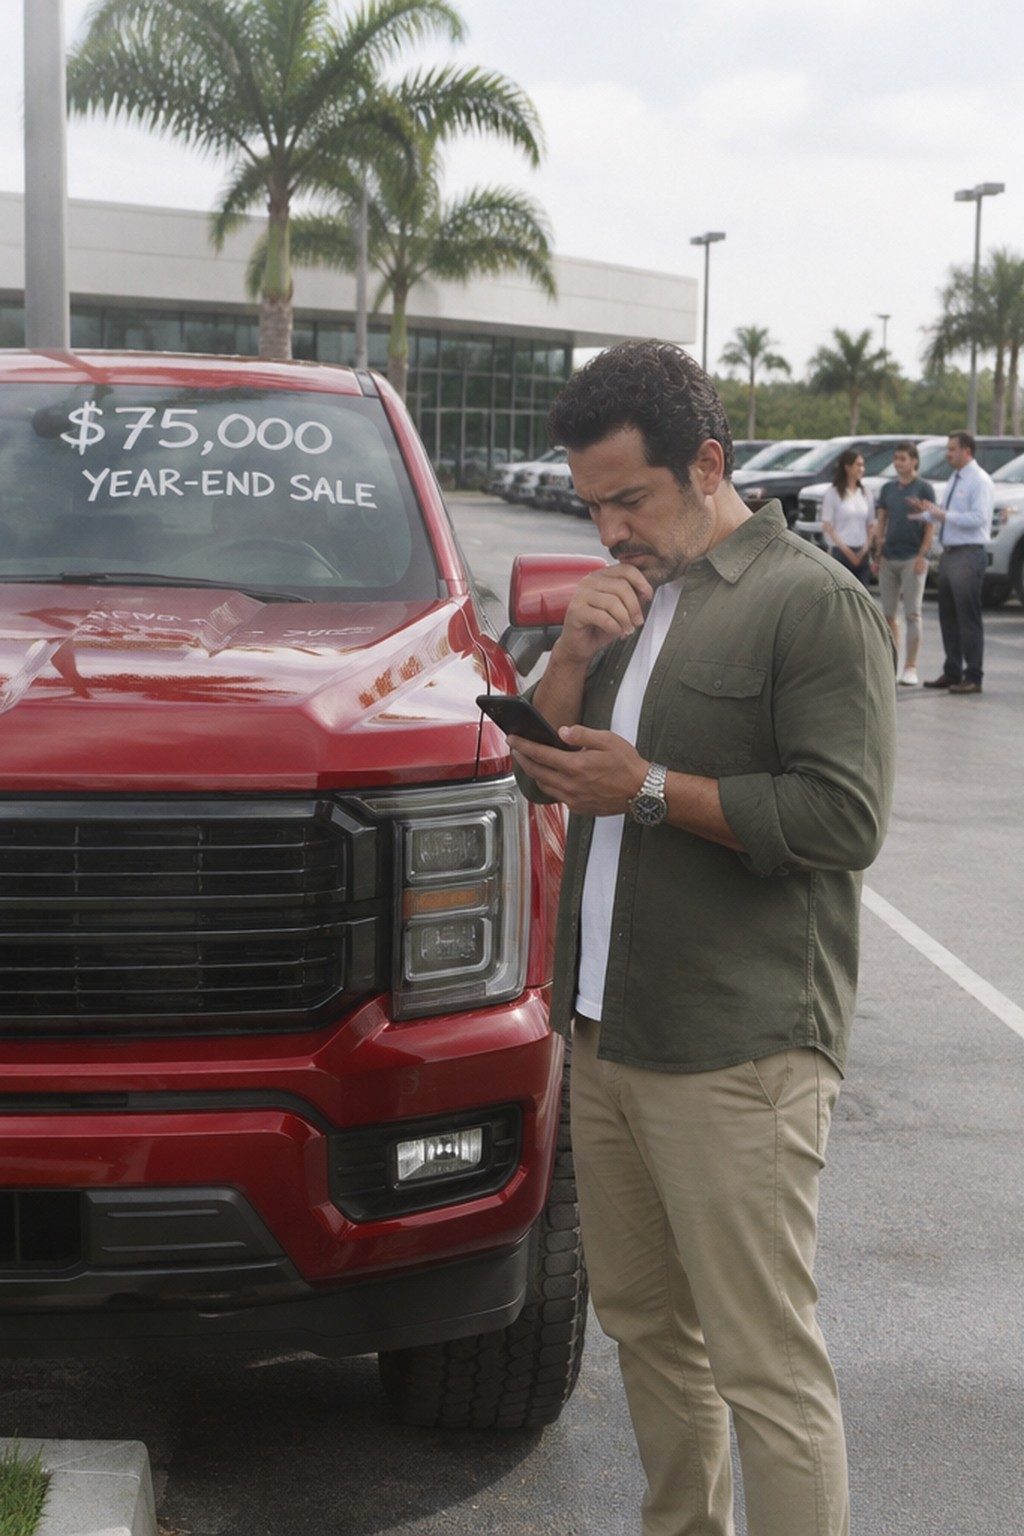
"Buy the truck before the end of the year, it’s a total write-off." That phrase gets repeated every November in WhatsApp groups, real estate offices, and at Latino chamber of commerce meetings all over Florida. The popular version says that if the vehicle is for your business, the government practically pays for it. The reality is different: a deduction is not a refund. The purchase can be an excellent tax decision—or a costly mistake approaching six figures. It depends on your tax bracket, the actual use of the vehicle, and your plans for the next three years.
This is the time to review it. Whatever you buy and put into service before December 31, 2026, counts for the return you’ll file in 2027. Let’s break it down.
Reality: A deduction reduces your taxable income, not your tax bill. You only recover the percentage equivalent to your marginal rate—that is, the rate you pay on your last dollar of profit.
Let’s use a round-number example. You’re an independent consultant or real estate agent filing on Schedule C (the form where a sole proprietor reports business activity). Your net profit puts you in the 32% federal bracket. You buy a pickup for $75,000 and use it 80% for business.
You recover about $21,000. You’re still putting around $54,000 out of pocket, plus about $4,500 in Florida state sales tax (6%), plus any county surcharge.
Here’s a detail many overlook. Florida has no state income tax, so your savings are only federal. The neighbor who recommended the purchase may have learned the trick in California or New York, where the deduction also reduces state tax. Here, the benefit is smaller.
For context, the average price of a new vehicle in the US surpassed $50,000 for the first time in September 2025, according to Kelley Blue Book. We’re talking about one of the largest purchases a small business makes in a year.
Reality: The weight of the vehicle changes everything.
The law known as the One Big Beautiful Bill Act (Public Law 119-21), signed in July 2025, made 100% bonus depreciation permanent for assets acquired and placed in service after January 19, 2025. It also raised the Section 179 limit to $2.5 million, adjustable for inflation. On paper, this allows you to deduct the full cost of many assets in the first year.
For vehicles, the IRS separates them as follows:
The GVWR is listed on the sticker inside the driver’s door frame. Don’t trust what the salesperson tells you—check the sticker.
Reality: The IRS requires that the vehicle be placed in service within the tax year. That means it must be in your possession and available for business use.
A vehicle reserved, factory-ordered, or pending delivery on January 2 does not count for 2026. If you’re negotiating now, confirm the delivery date in writing.
Financing, on the other hand, is not an obstacle. You can deduct the full cost even if you’ve only paid the down payment. Still, it’s wise to review your cash flow: you’ll get the deduction in 2027 and make monthly payments through 2031.
Reality: What determines the deduction is use, not the name on the title.
To use Section 179 or bonus depreciation on a vehicle, qualified business use must be greater than 50%. Commuting from your home to your fixed office is considered personal use, not business. Visiting properties, clients, job sites, or meeting with prospects is business use.
The most important thing in an audit is a contemporaneous mileage log: date, destination, purpose, and miles, recorded at the time—not reconstructed in April. Today, there are apps that do this automatically using your phone’s GPS. If you can’t prove the percentage of business use, the IRS can reduce or eliminate the deduction.
This point matters more than it seems. The IRS estimates a gross tax gap of $696 billion for fiscal year 2022, and underreporting of business income is a major component. Vehicle expenses for self-employed individuals are among the first items reviewed.
If you operate as an S-Corp, the approach changes. The vehicle can be titled in the corporation’s name, or you can own it personally and have the company reimburse you under an accountable plan. Each option has different consequences for your payroll and deductions.
Reality: Accelerating the deduction can have costs that show up later.
Using the standard mileage rate is a legitimate option. In 2025, it was 70 cents per mile, according to IRS Notice 2025-5, and it’s updated annually. With this method, you don’t deduct the vehicle’s cost, but you simplify recordkeeping and avoid recapture risk.
A real estate agent who drives 20,000 business miles a year with a moderately priced vehicle may come out ahead using the standard mileage rate rather than buying a heavy truck just for the deduction. The key is to choose this method in the first year you use the vehicle for business. If you start with accelerated depreciation, you can’t switch to the standard mileage rate for that vehicle.
Buying before December 31 usually makes sense when these four conditions are met:
If any of the four are missing, the purchase may still be good. The difference is that it becomes a business decision, not a tax strategy.
This decision isn’t made at the dealership—it’s made with your numbers. The right question isn’t "Can I deduct it?" The question is: "How much does it really cost me after taxes, and what effect will it have on my plans for the next three years?"
At La Familia Multiservices, we work with business owners, consultants, agents, and investors in Florida who want to make these decisions with concrete projections. Before you sign, we can model your scenario: bracket, structure (Schedule C, LLC, or S-Corp), depreciation method, and impact on future credit applications. Schedule your year-end planning consultation at www.lafamiliamultiservices.com.